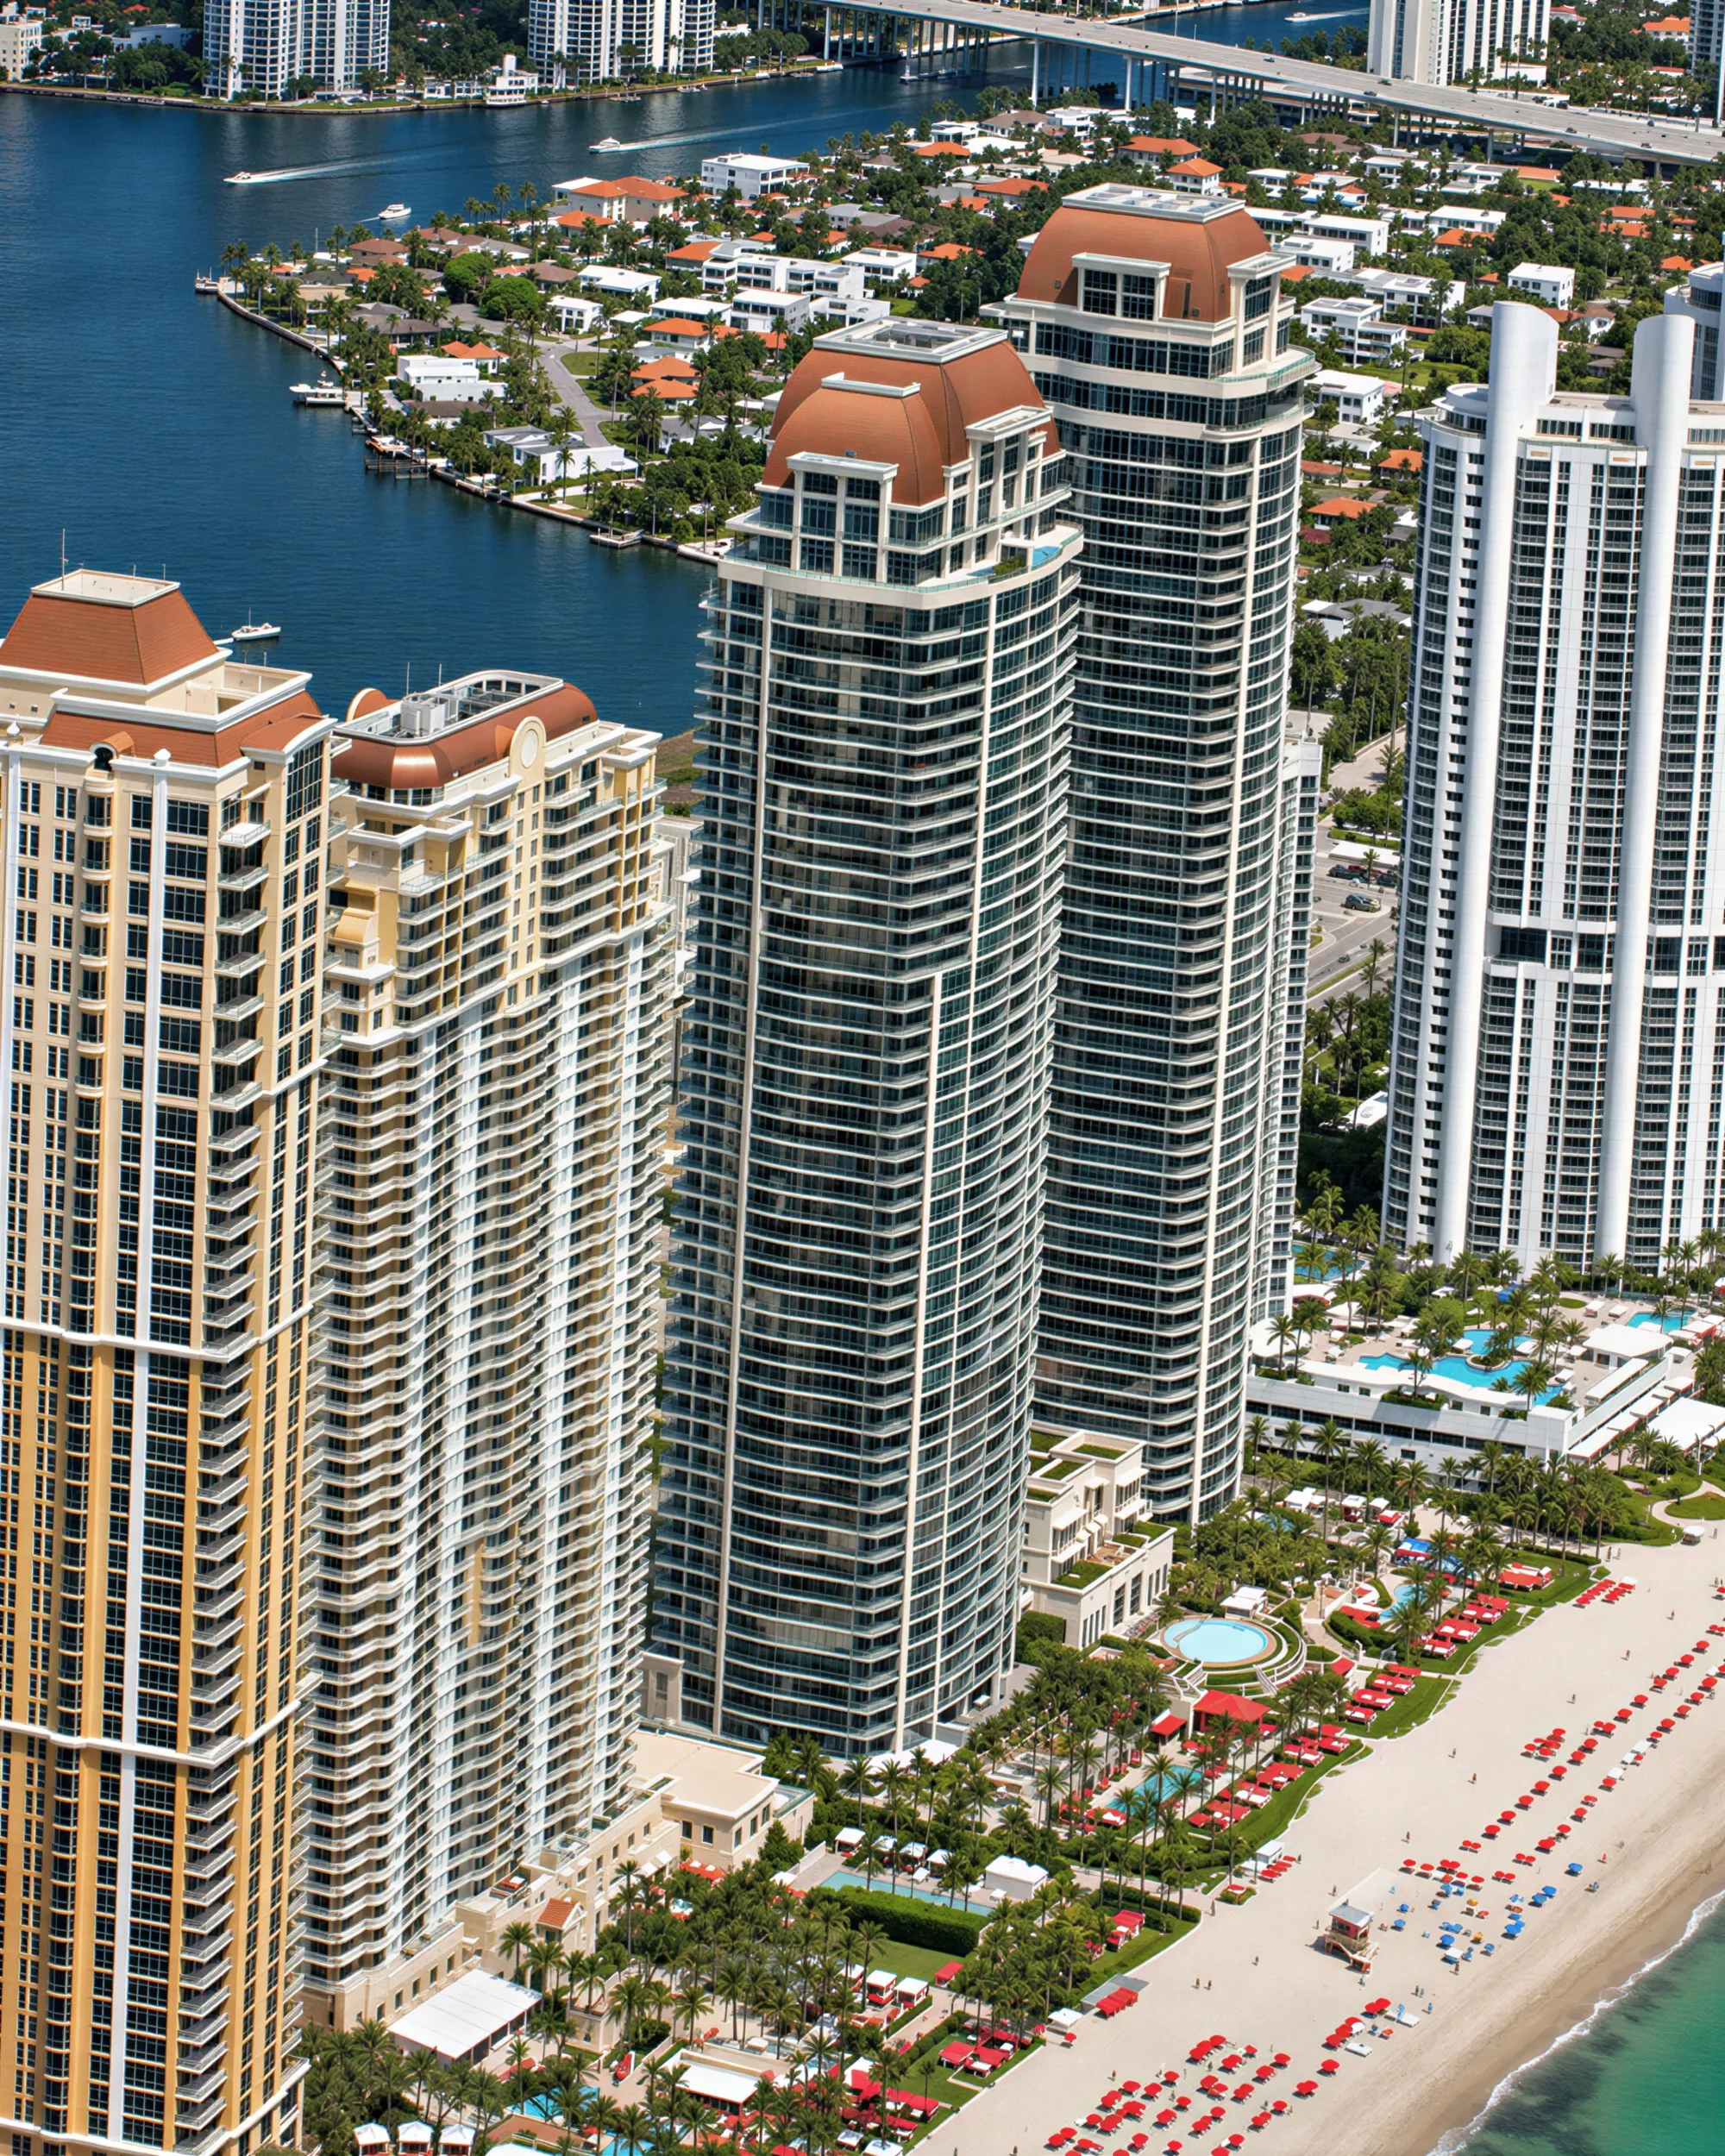
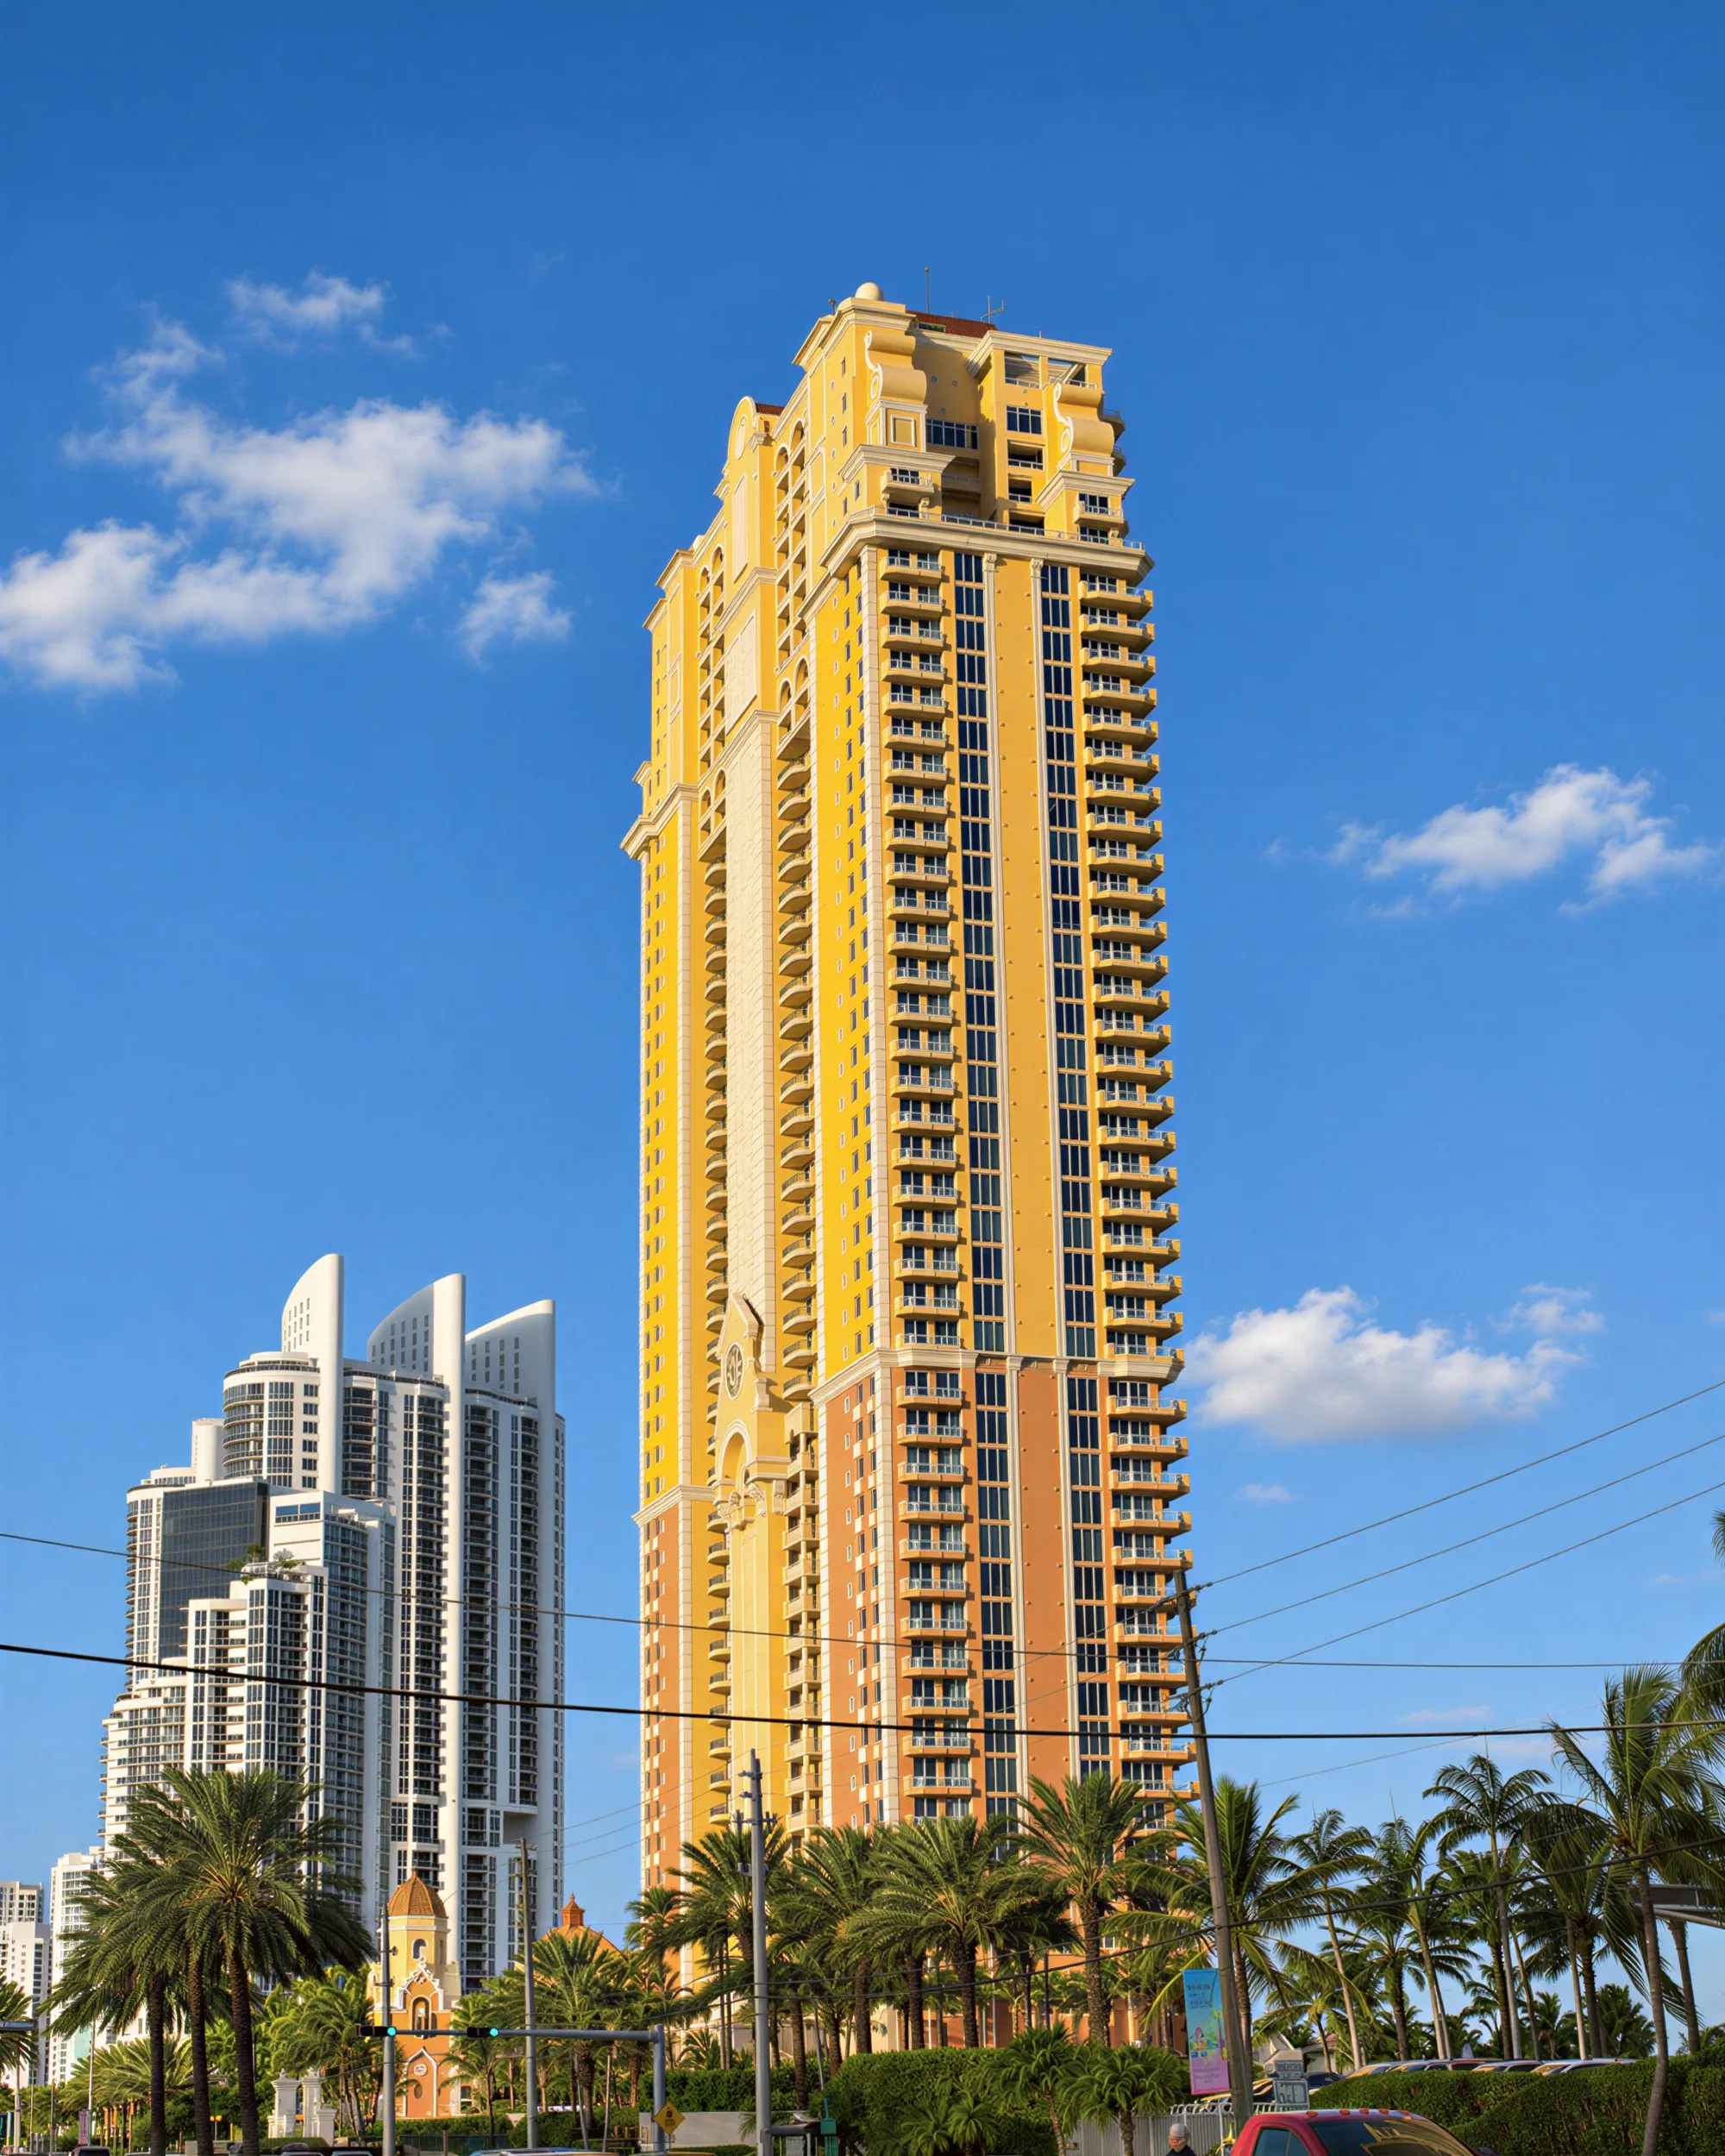
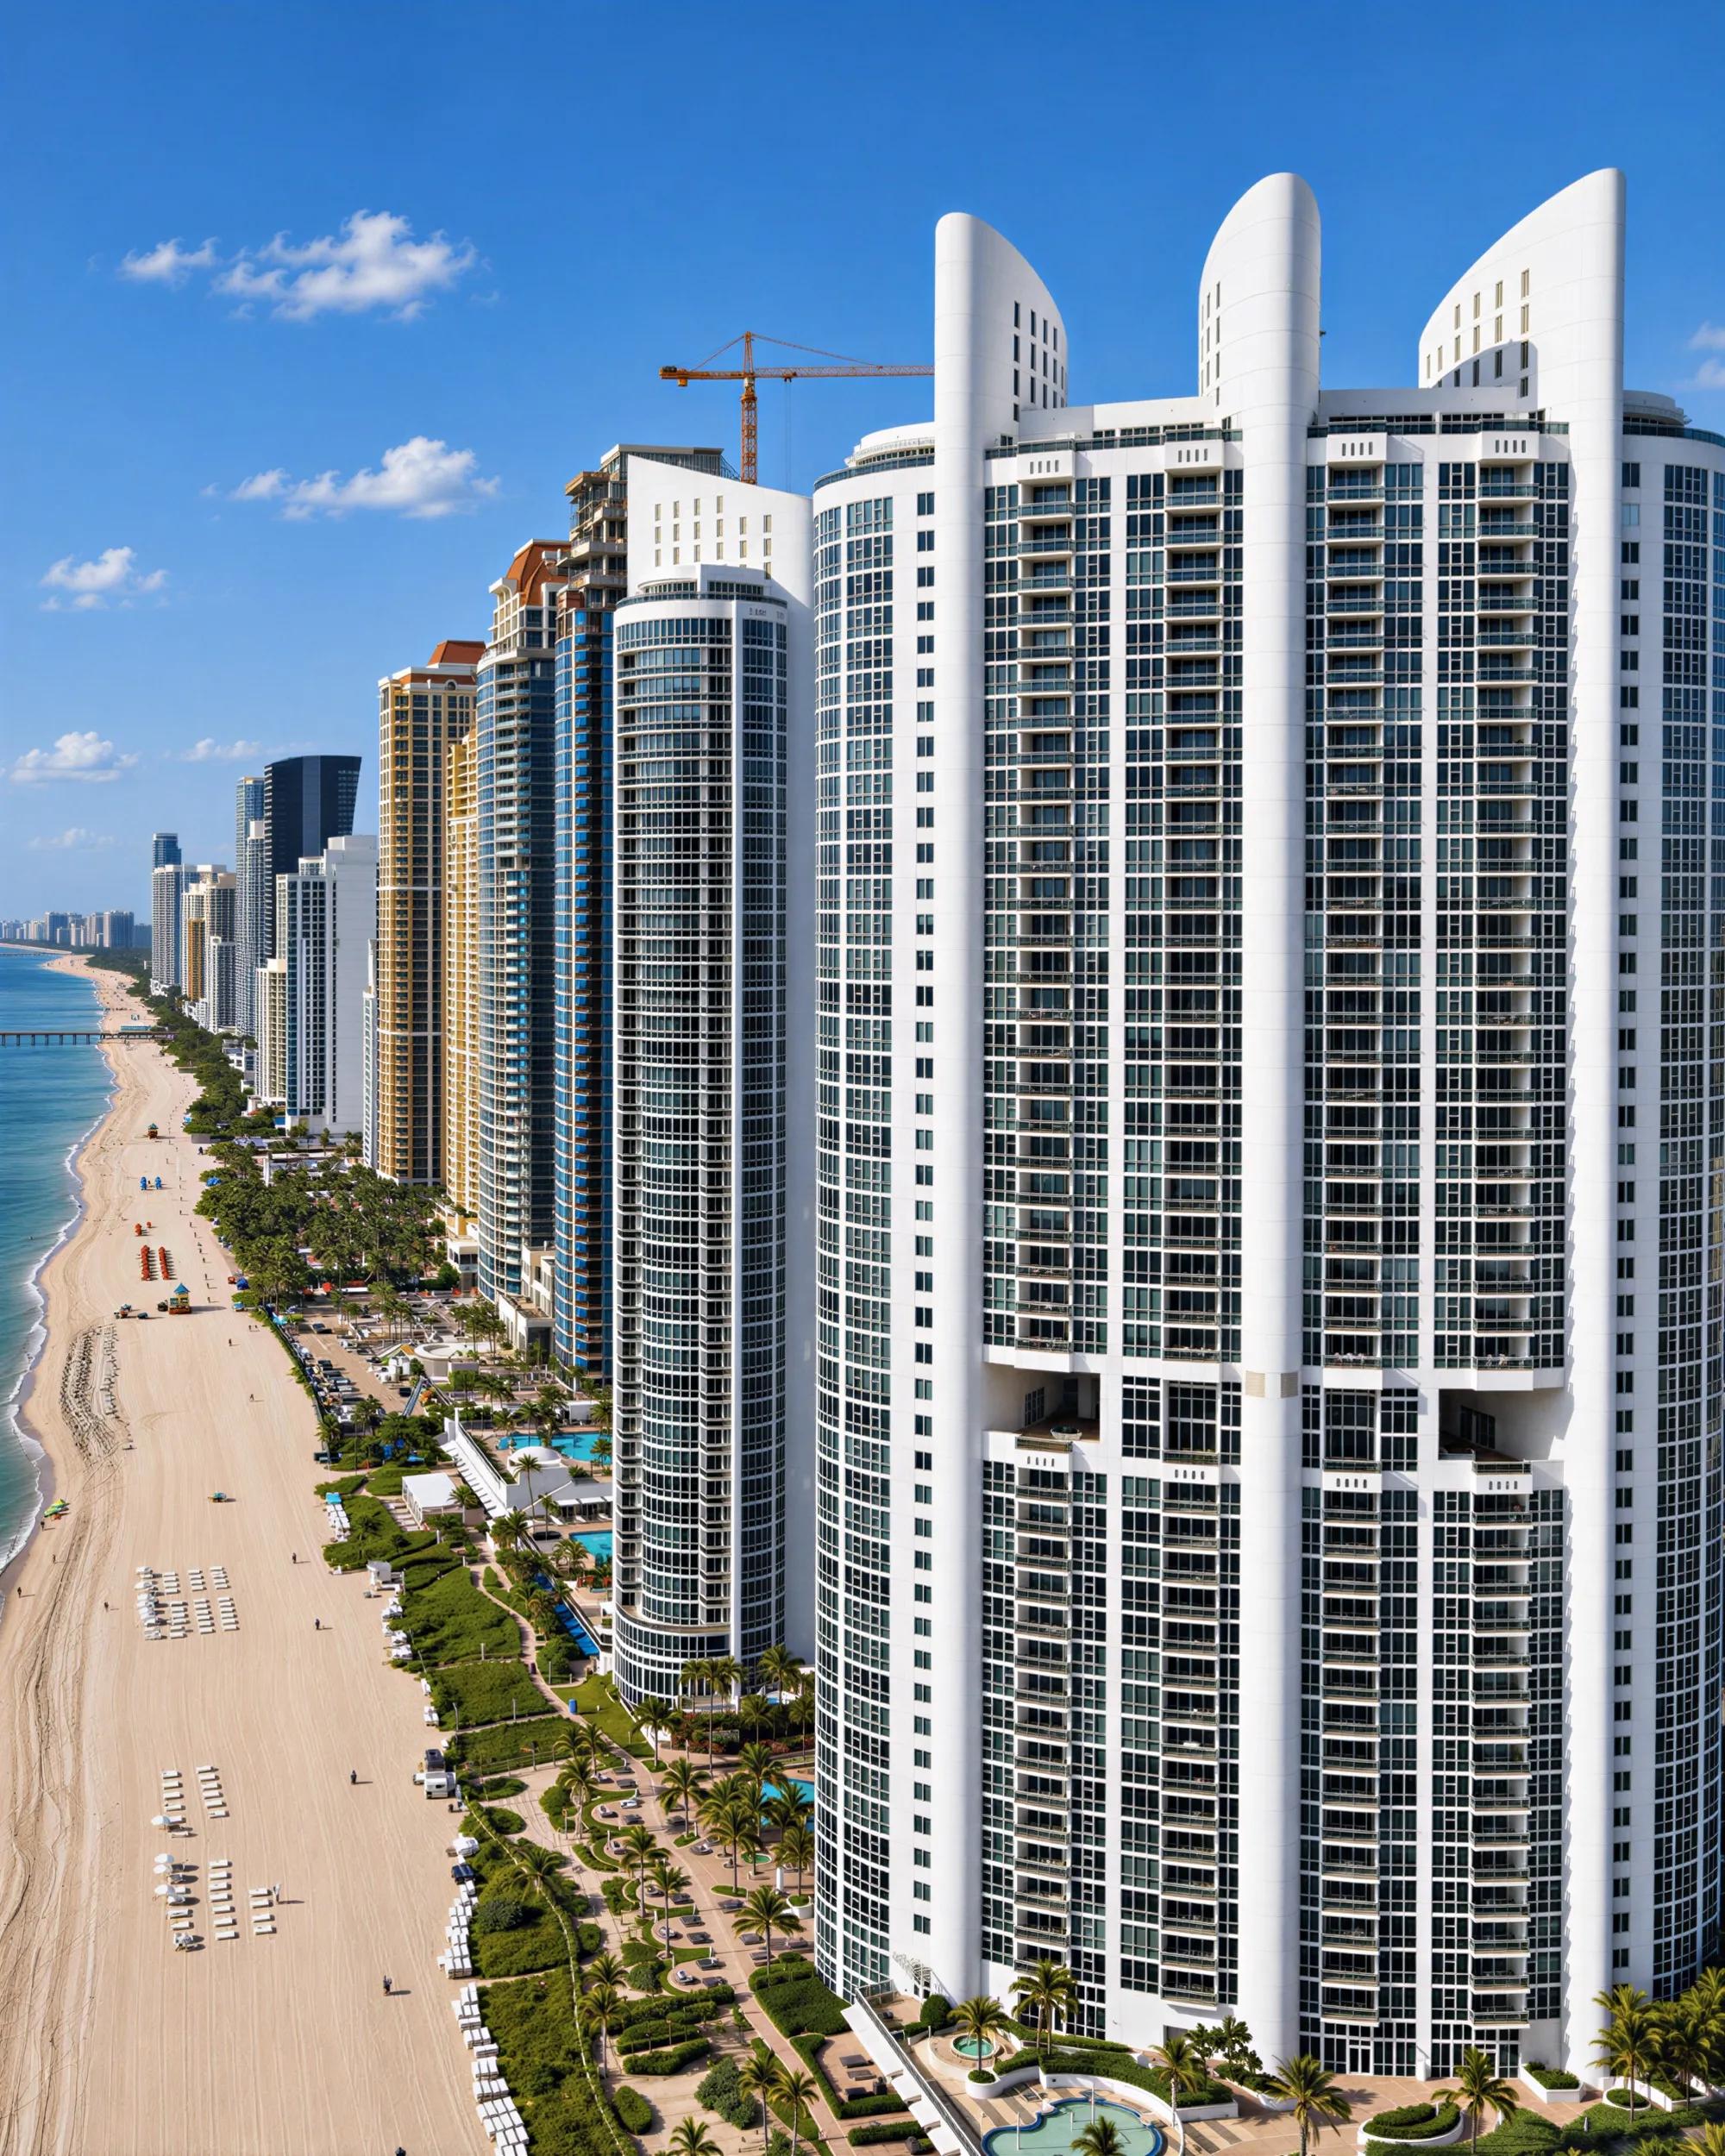
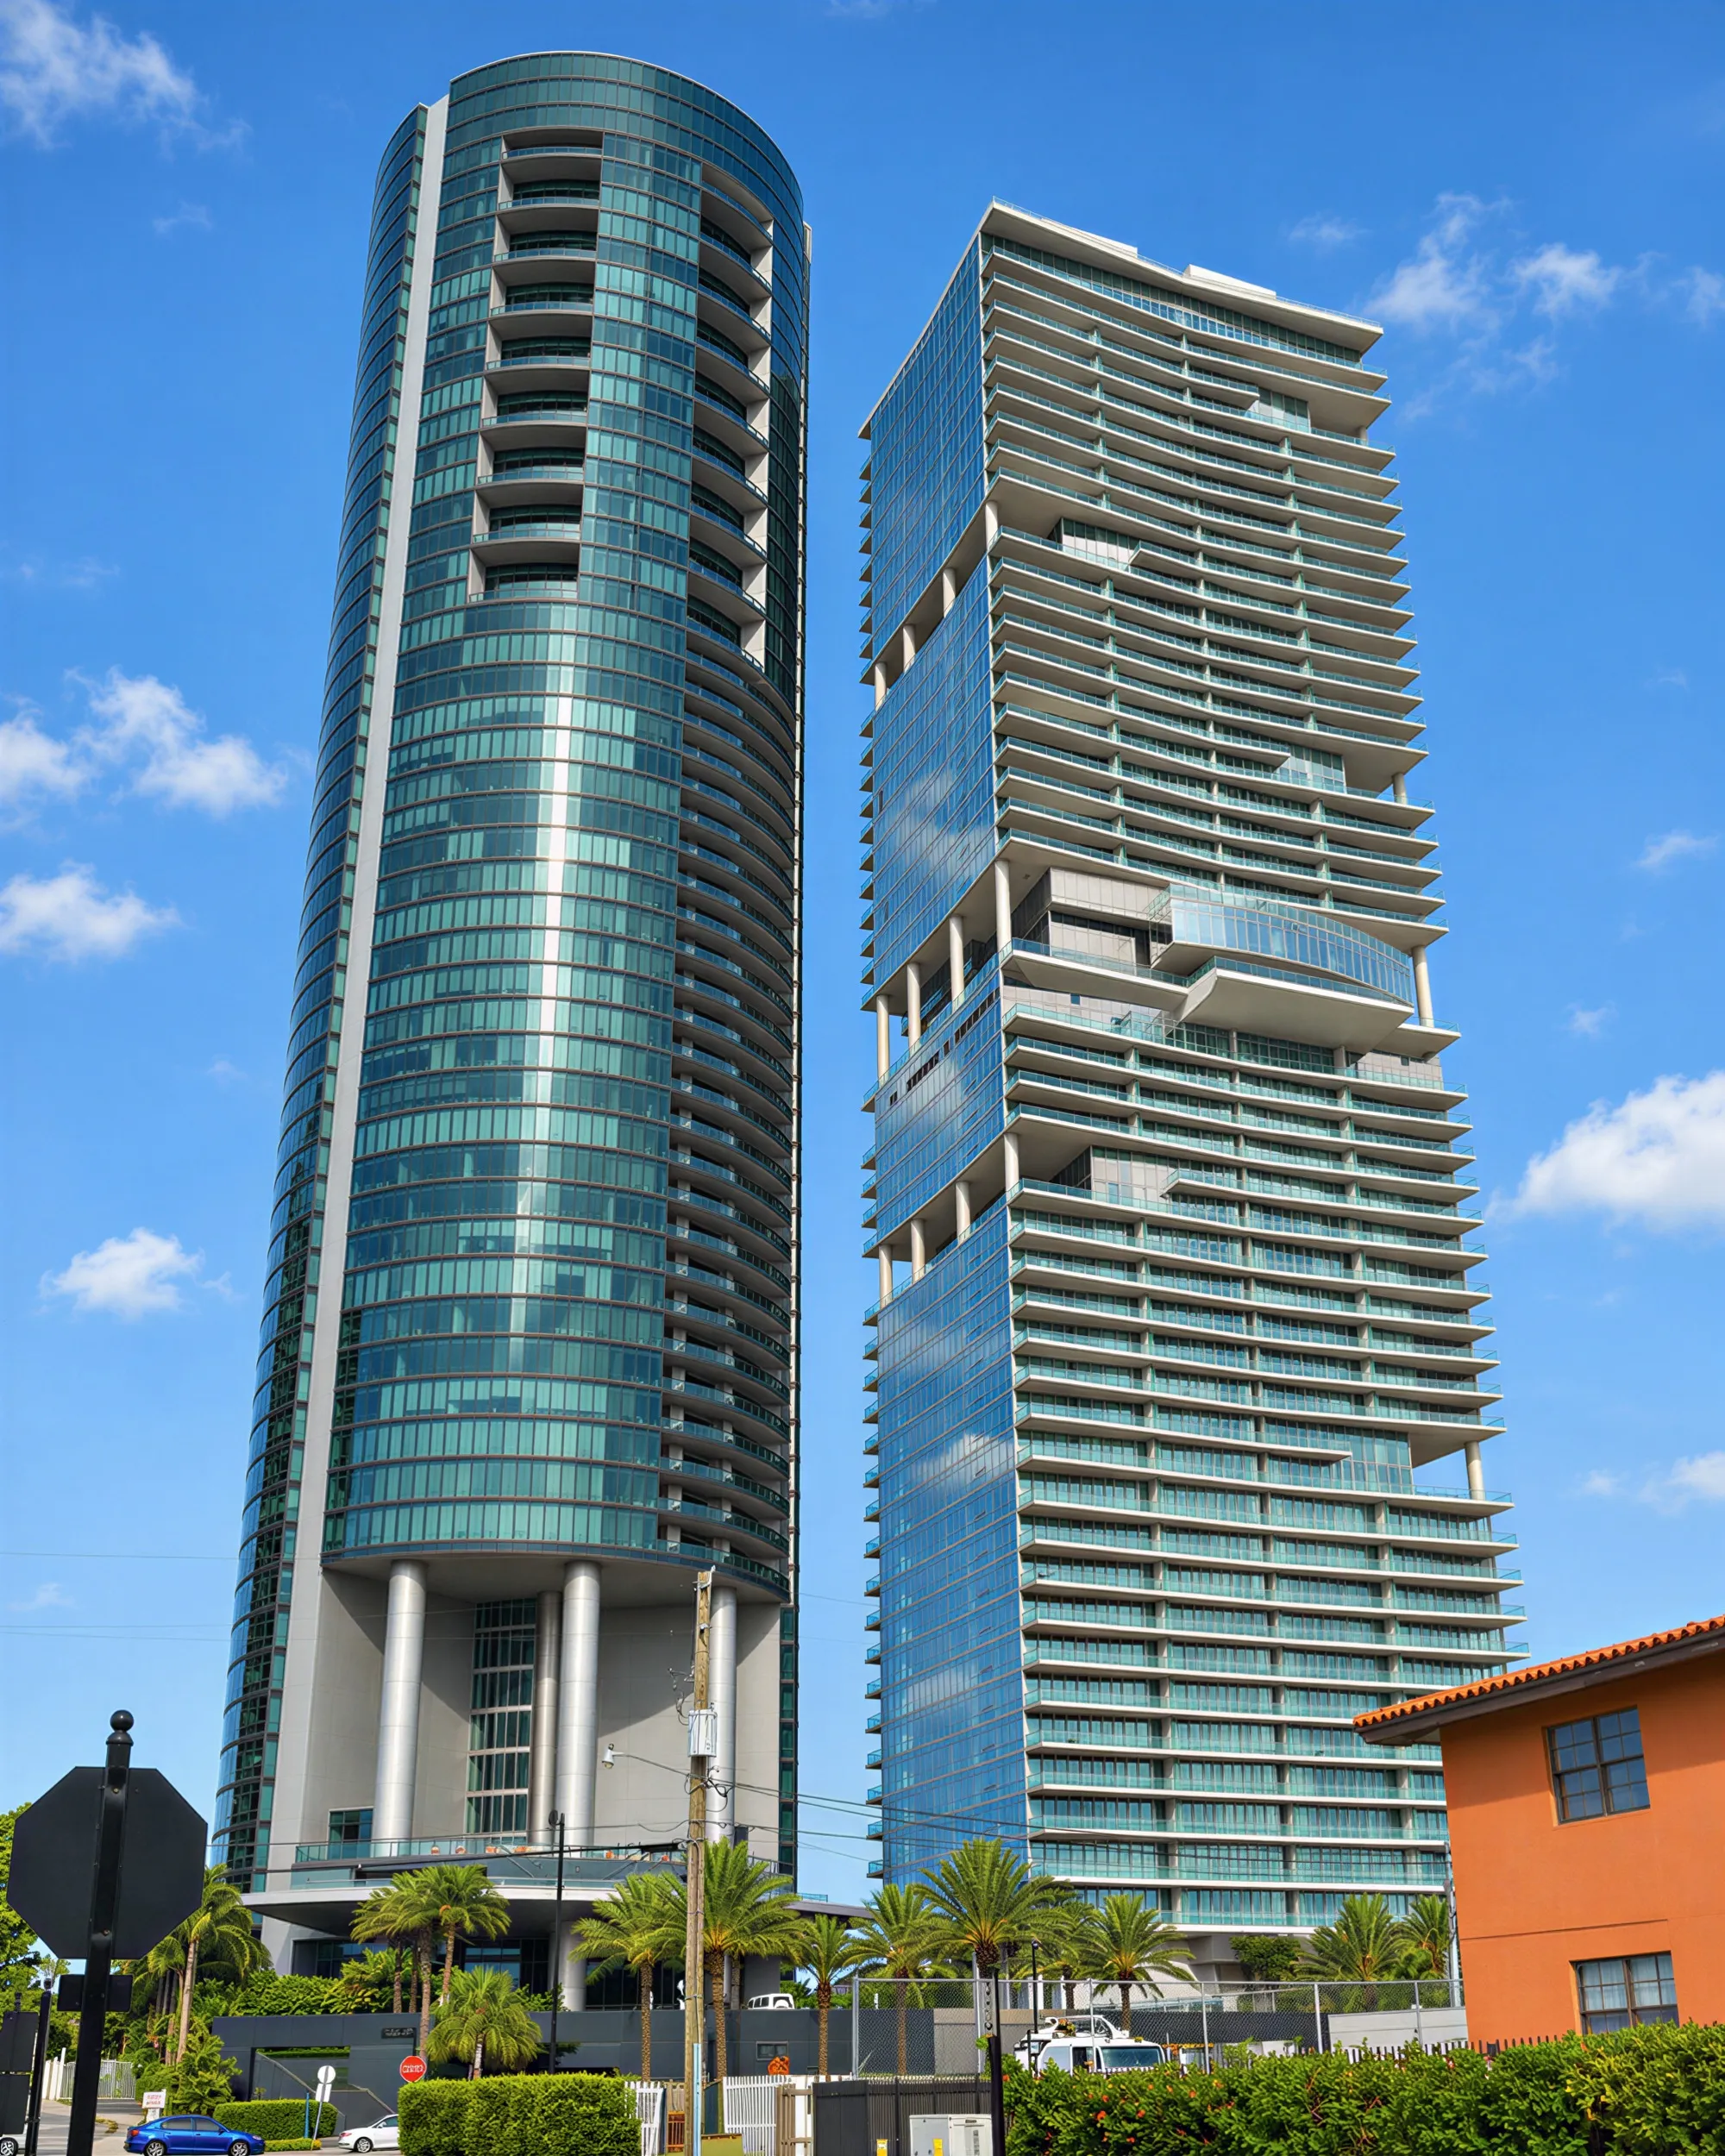
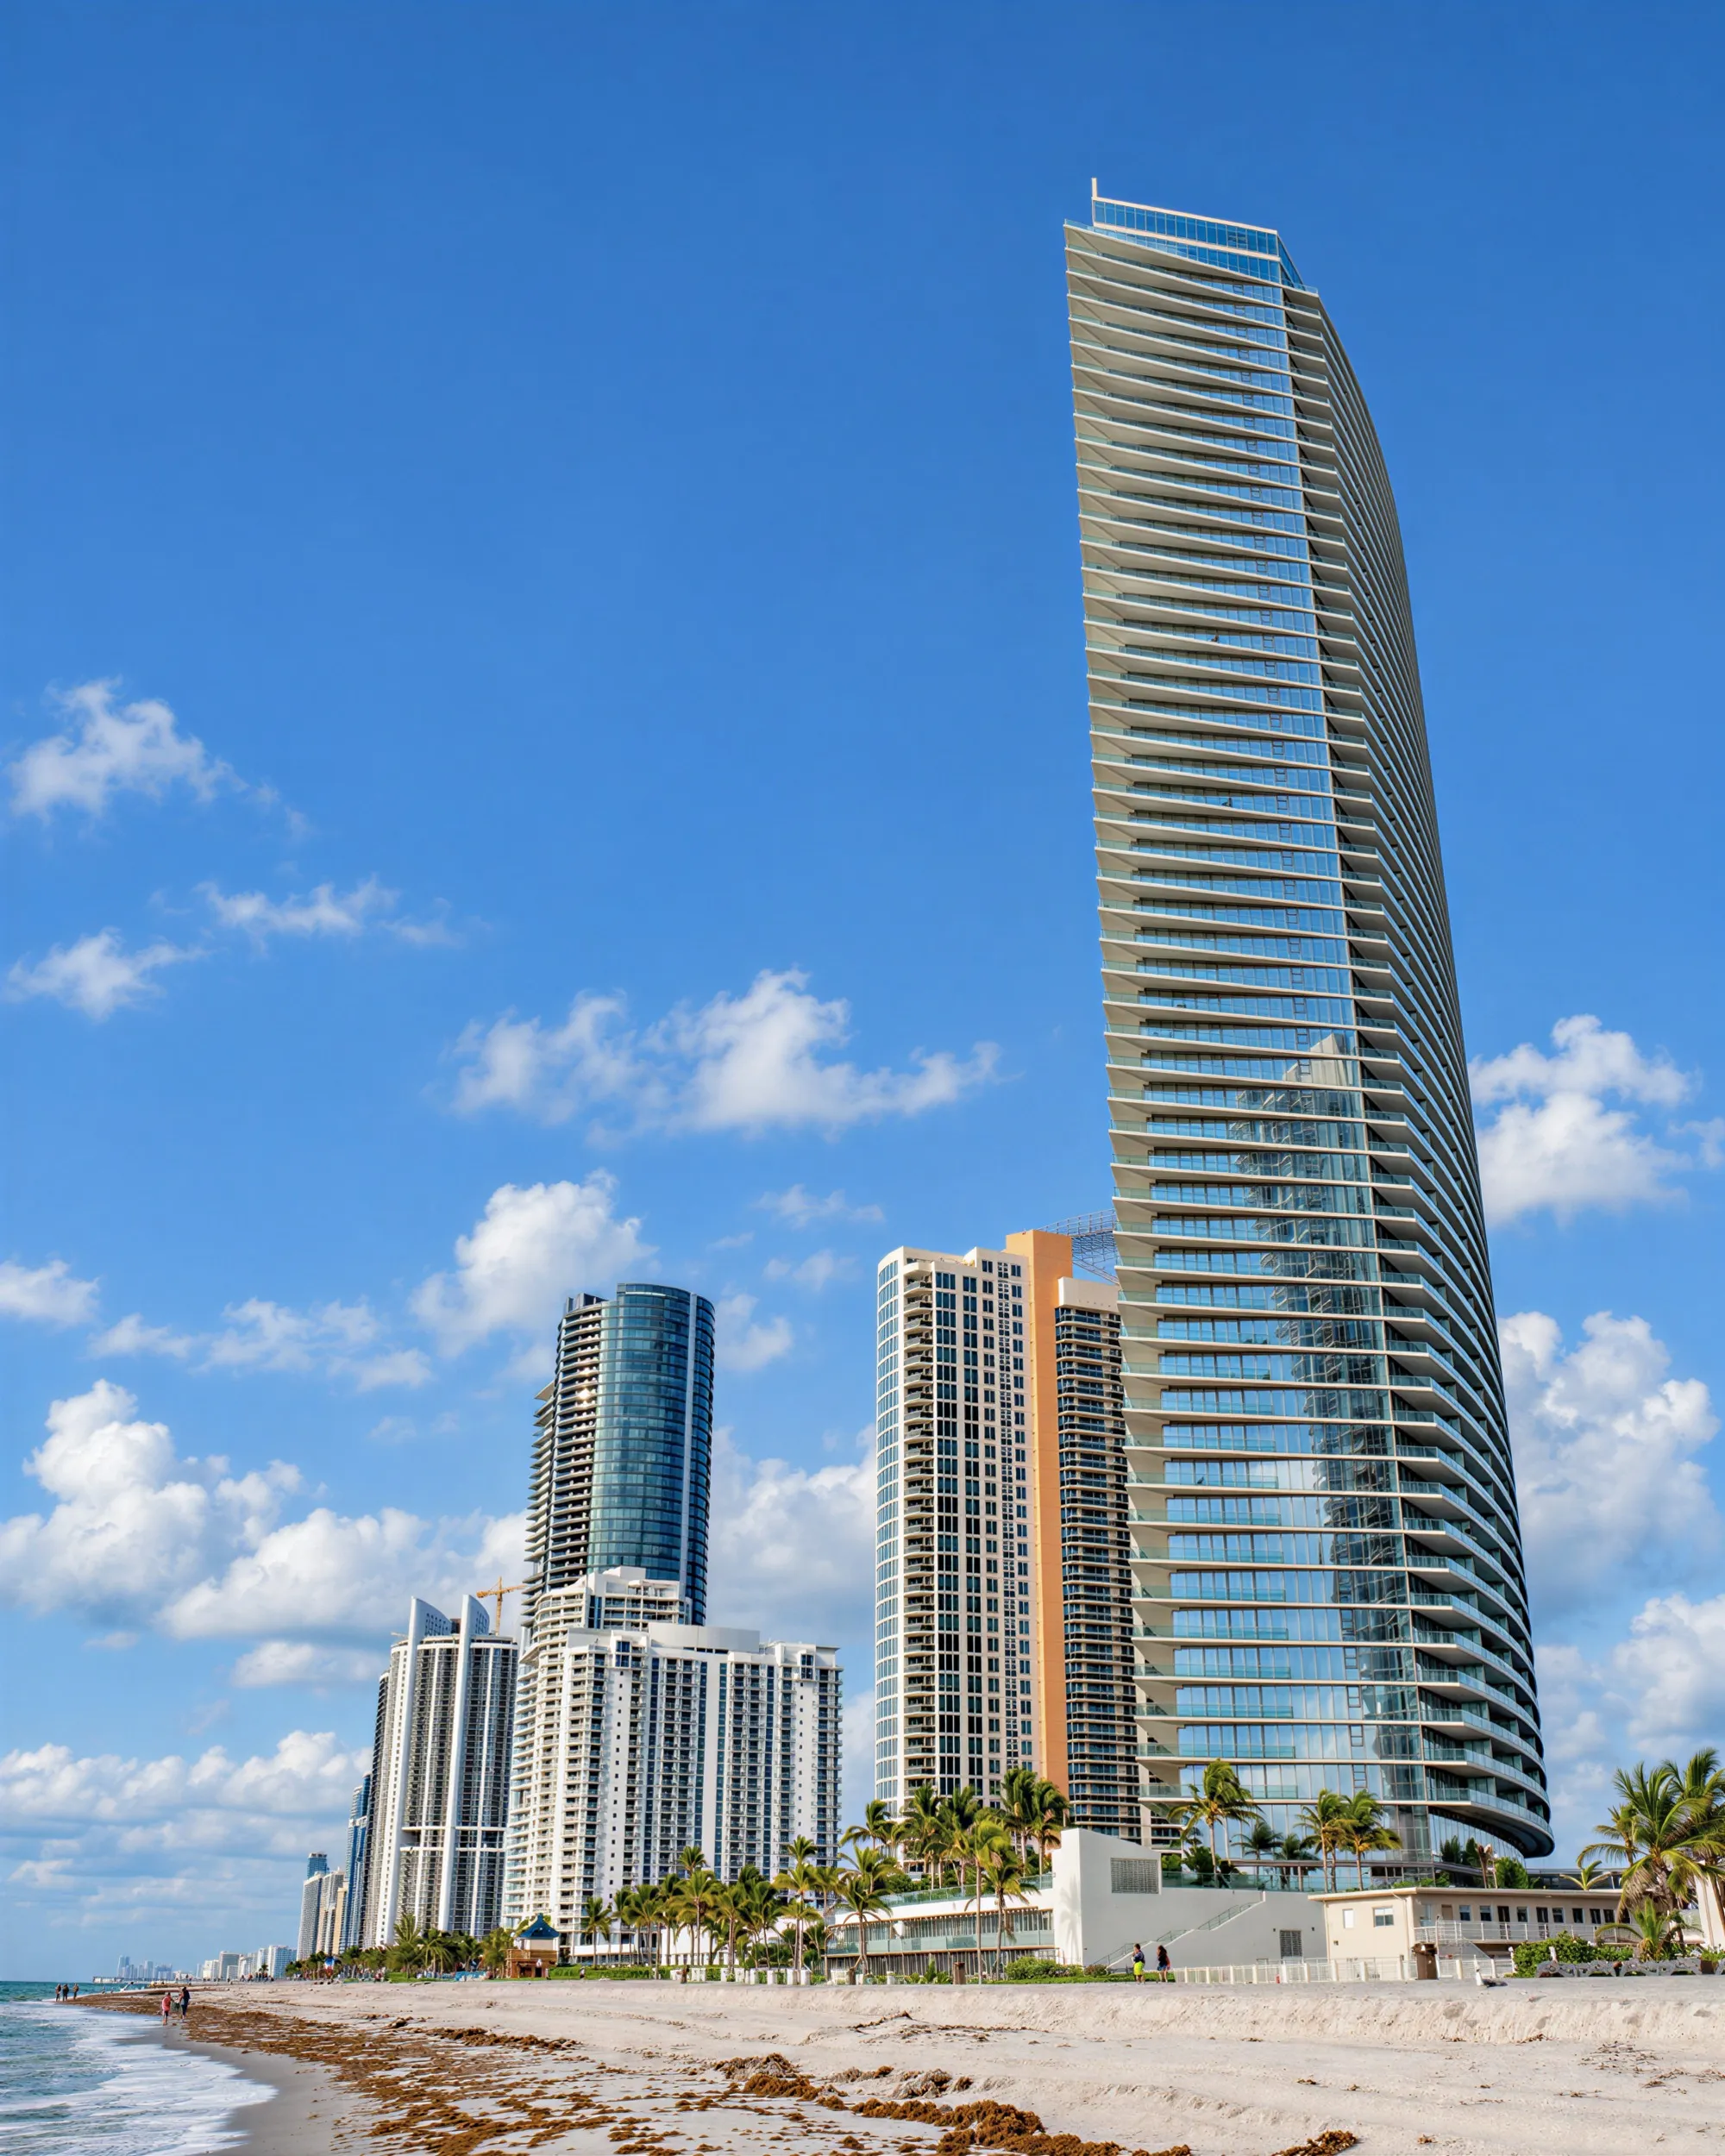
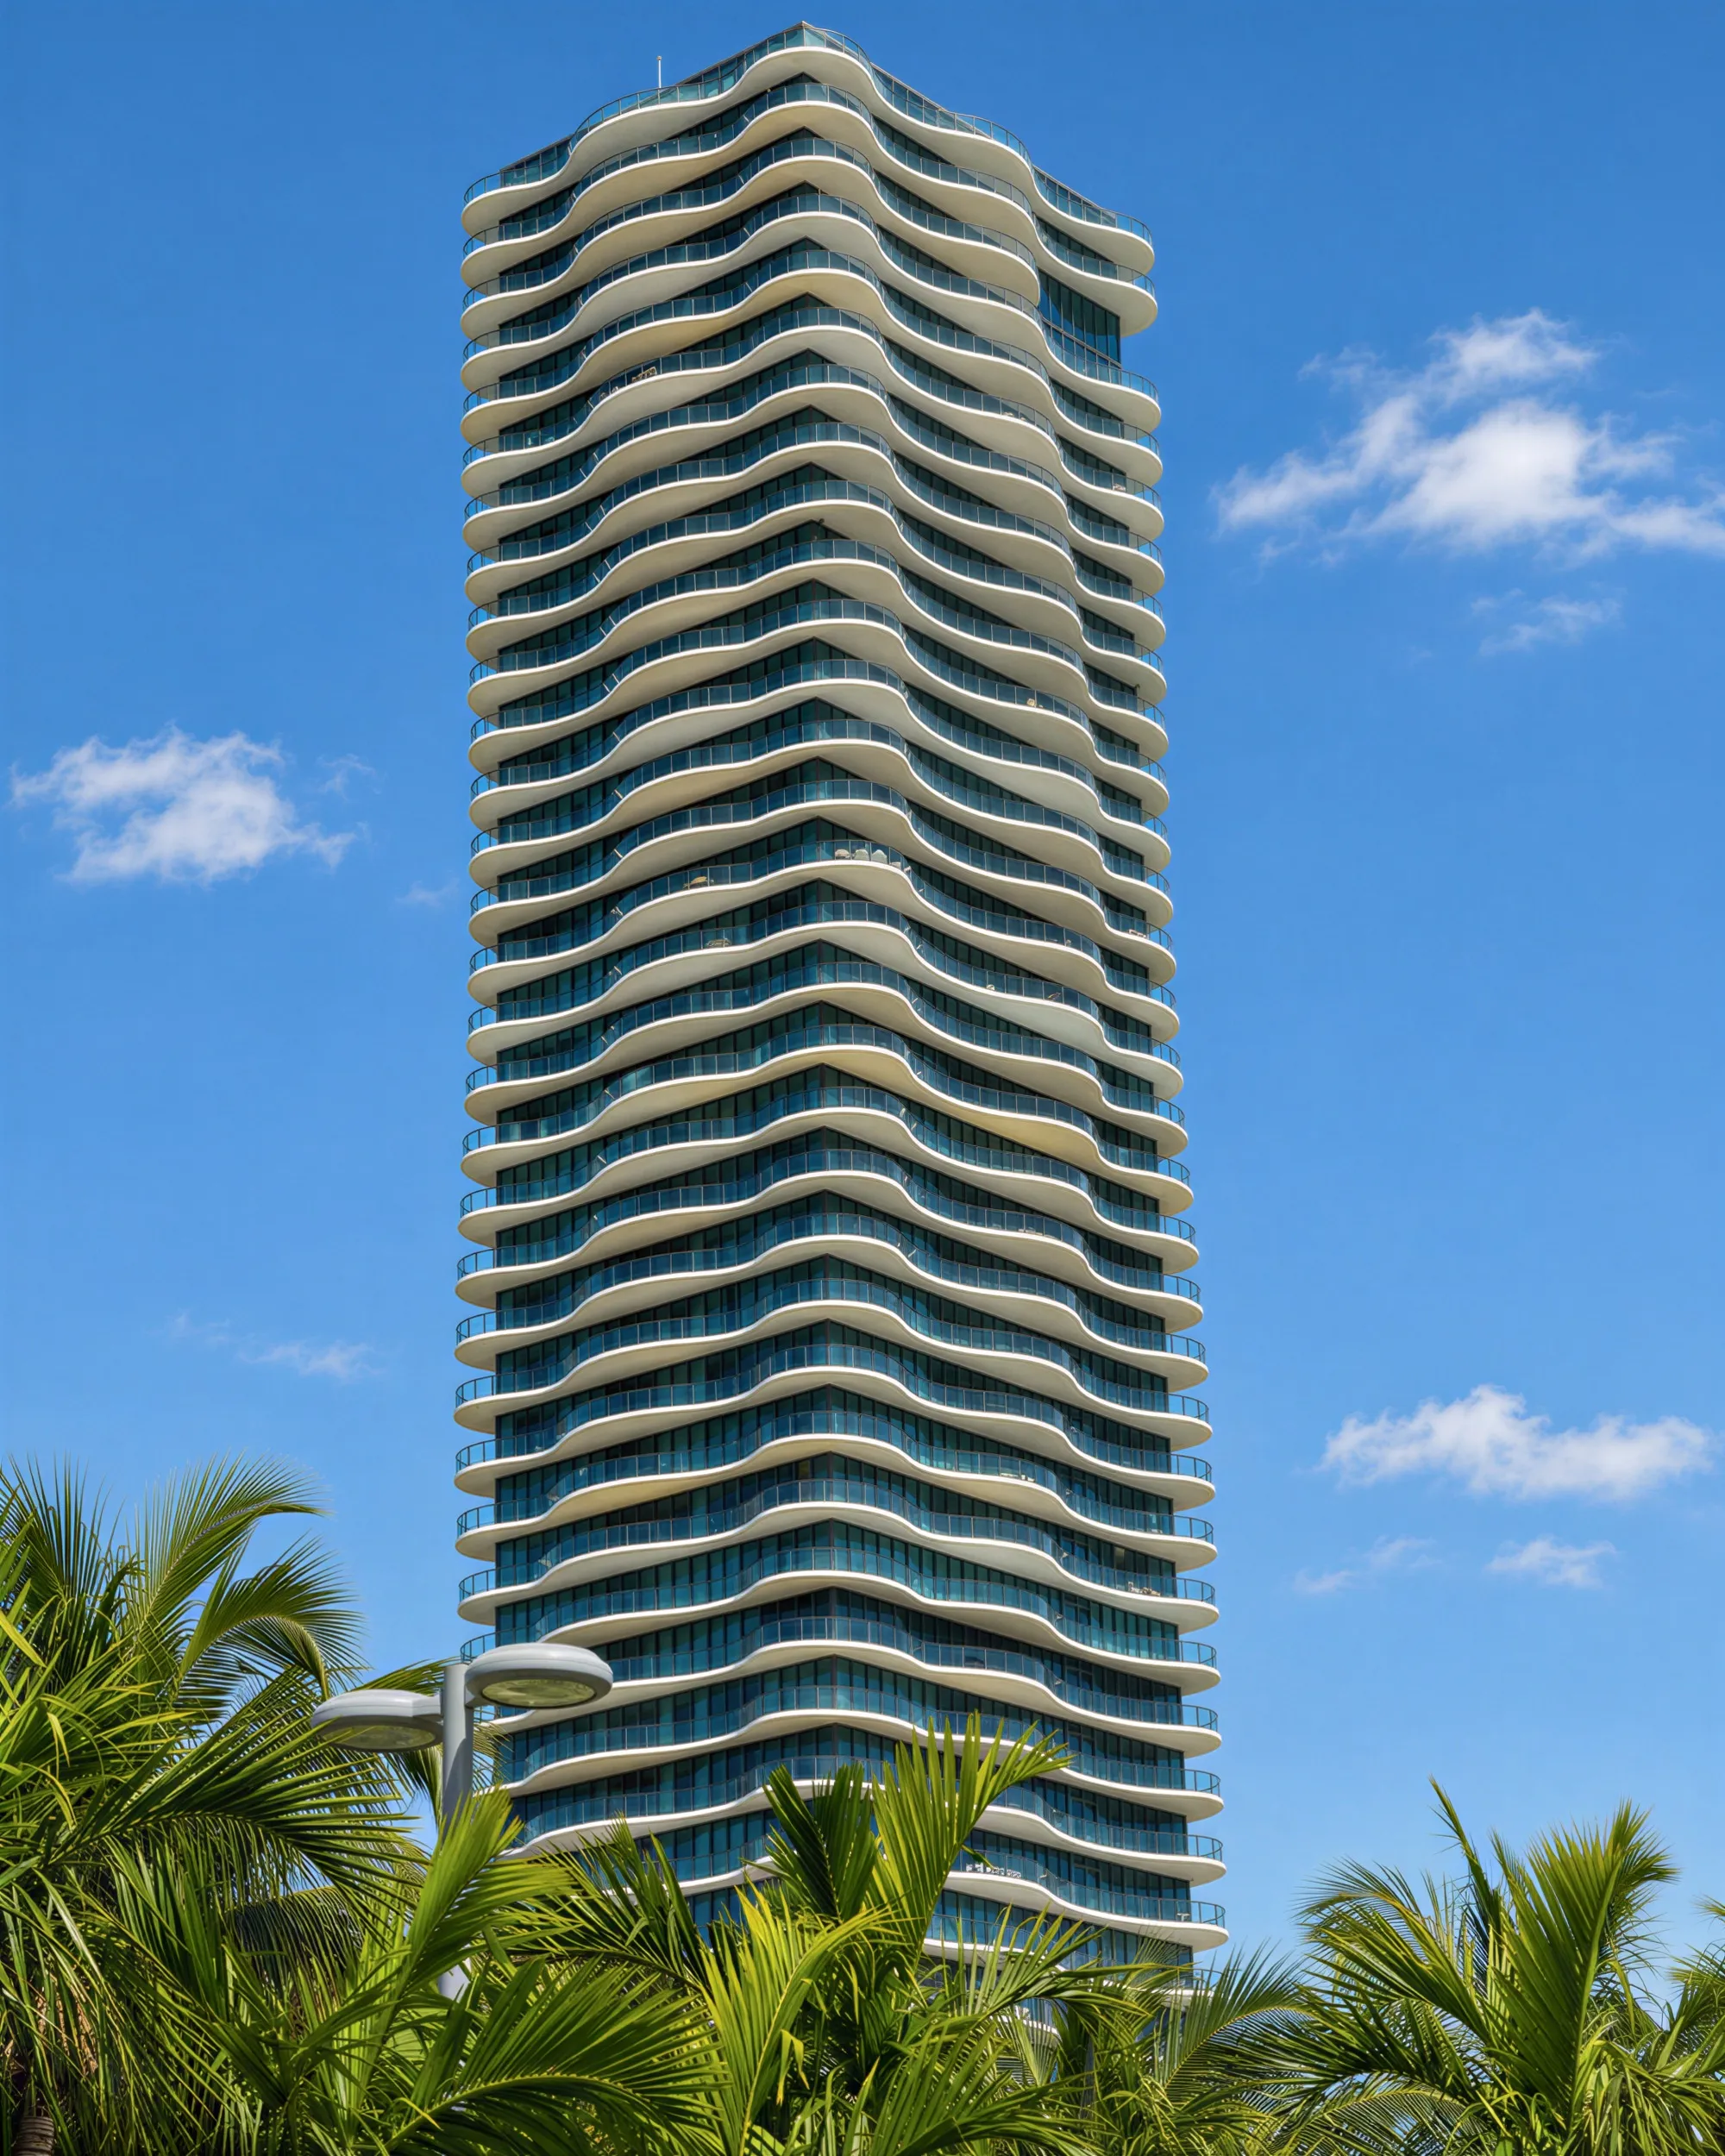
The tower stands outside the 1% flood area on both FEMA maps, but the revised maps of 2027 bring the zone of storm waves much nearer. On the current maps, in force since 11 September 2009, the building itself lies in Zone X (unshaded), where flood risk is minimal. Toward the beach the parcel passes through Zone X (shaded), with a 0.2% chance of flooding in any year, and then Zone AE, the 1% annual-chance area, at a base flood elevation of 8 feet (2.4 m). There a mortgage lender usually requires flood insurance. Nearer the water it lies in Zone VE, at 10 feet (3.0 m).
Zone VE is where storm waves strike and building rules are strictest. A base flood elevation is the height water is expected to reach in a 1%-a-year flood, measured from the map's reference level (NGVD29 on the current maps), never a depth of water above the ground.
The revised maps, effective 19 February 2027, place the building in Zone X (shaded) and the beach side of the parcel in Zone VE; the AE band between them disappears. The revised VE zone has a base flood elevation of 12 feet, measured from a newer reference level (NAVD88), so the figures do not compare directly. It begins about 50 meters east of the building's map point, against about 130 meters today: some 80 meters closer, give or take 5. These are readings of FEMA's National Flood Hazard Layer, not official flood-zone determinations.
Like all of Sunny Isles Beach and Golden Beach, the address sits in Miami-Dade Storm Surge Planning Zone B, where storm surge, the sea water a hurricane pushes ashore, is a risk from Category 2 storms upward. The county orders evacuations by each storm's track and projected surge, not by category alone.
Flood insurance. The National Flood Insurance Program (NFIP) covers up to $250,000 for a residential building and $100,000 for contents. A condominium association's building policy can reach $250,000 multiplied by the number of units, or $36.5 million for the 146 units in the recorded condominium. At these values, cover above the NFIP limits is bought privately.
Windstorm insurance. Citizens, Florida's state-backed insurer of last resort, may not write a unit owner's policy where the unit's combined dwelling and contents replacement cost is $700,000 or more. The threshold rises to $1 million in counties where the state insurance regulator finds too little competition. What counts is the cost of rebuilding and refitting the unit, not the price paid; the association's policy for the building is a separate matter. An insurance agent can say whether a given unit qualifies.